Investor/Analyst Briefing 9M25
Choose
Choose
1H26
1Q26
FY25
Others
9M25
1H25
1Q25
FY24
9M24
1H24
1Q24
FY23
9M23
1H23
1Q23
9M25
Investor/Analyst Briefing September 2025
Financial Highlight
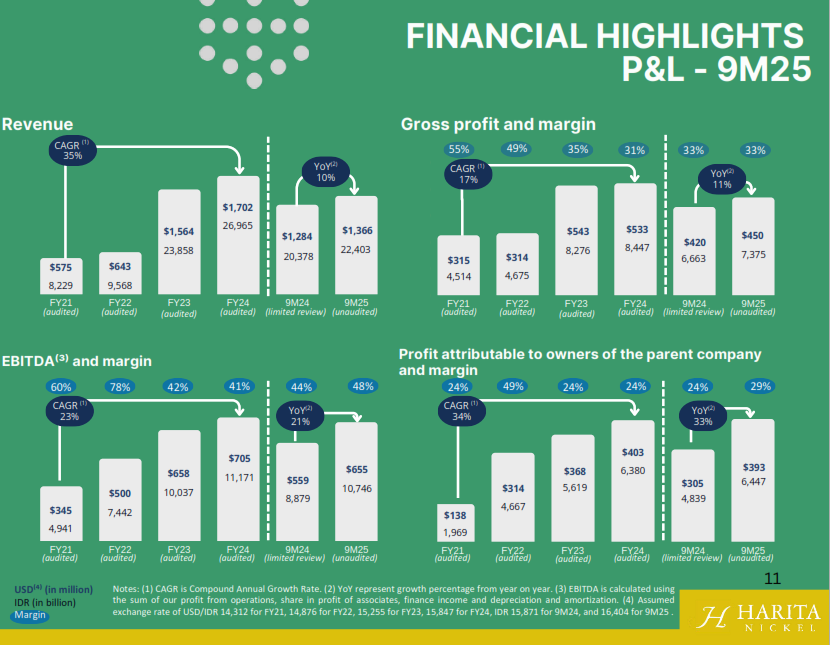
- GPM YoY is stable, not much changes in ASP acost structure, while EBITDA is up by 21%.
- Profit Attributable to Owners of the Parent Company growth driven by higher ownership in ONC and new production capacity from KPS.
Bussines Highlight
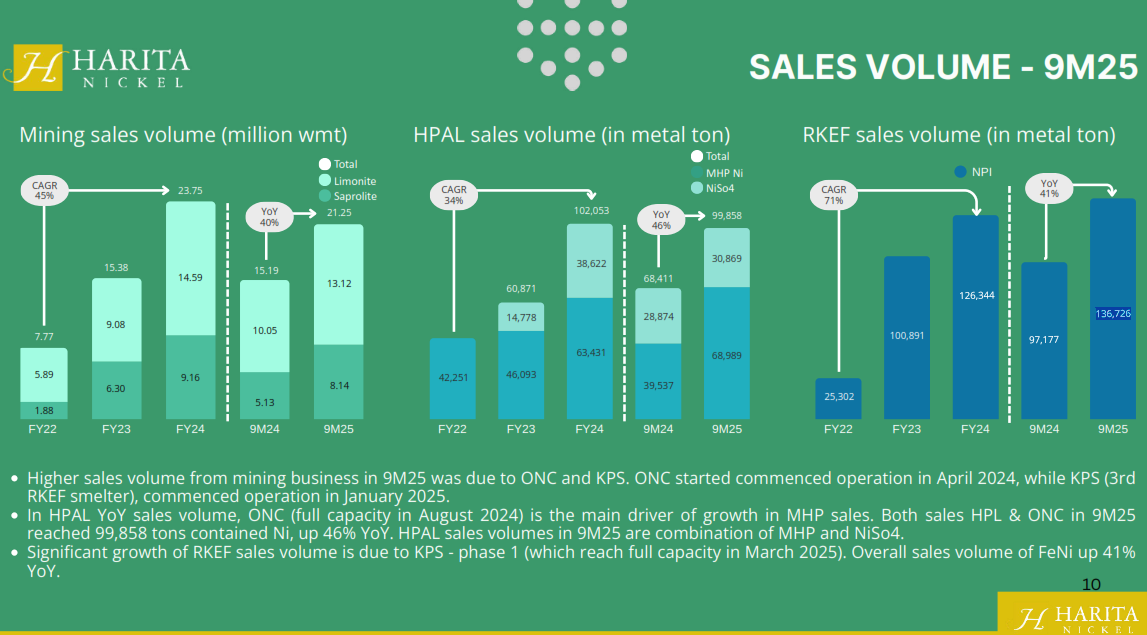
- Higher sales volume from mining business in 9M25 was due to ONC and KPS. ONC started commenced operation in April 2024, while KPS (3rd RKEF smelter), commenced operation in January 2025.
- In HPAL YoY sales volume, ONC (full capacity in August 2024) is the main driver of growth in MHP sales. Both sales HPL & ONC in 9M25 reached 99,858 tons contained Ni, up 46% YoY. HPAL sales volumes in 9M25 are combination of MHP and NiSo4.
- Significant growth of RKEF sales volume is due to KPS - phase 1 (which reach full capacity in March 2025). Overall sales volume of FeNi up 41% YoY.