Investor/Analyst Briefing 1Q23
1Q23
Investor/Analyst Briefing May 2023
-
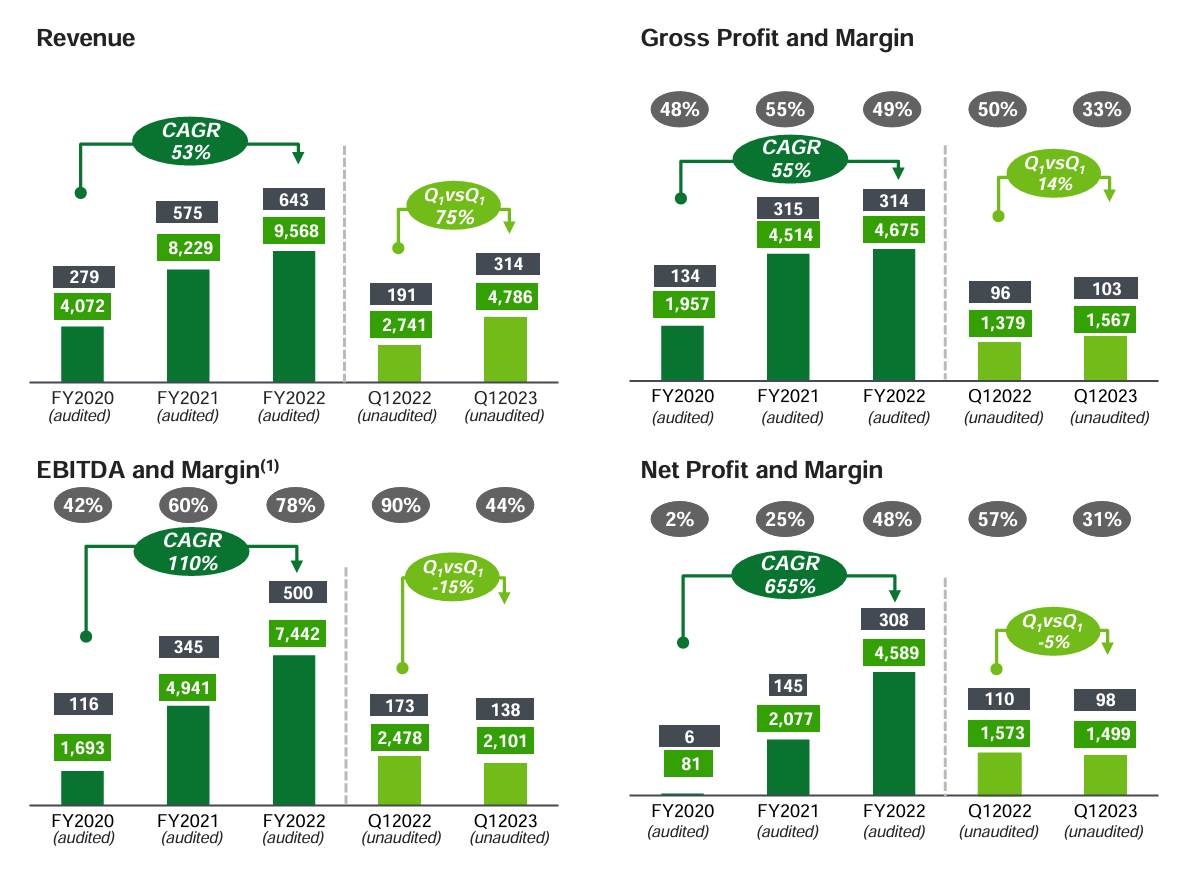
Strong track record of revenue growth driven by production ramp up of nickel processing facilities.
-
Healthy profitability margin with double digit gross profit, EBITDA and net profit margin.
-
Slight dip in Q1vs Q1 performance's EBITDA and Net profit due to the lower of share in net profit associates coming from HPAL.
-
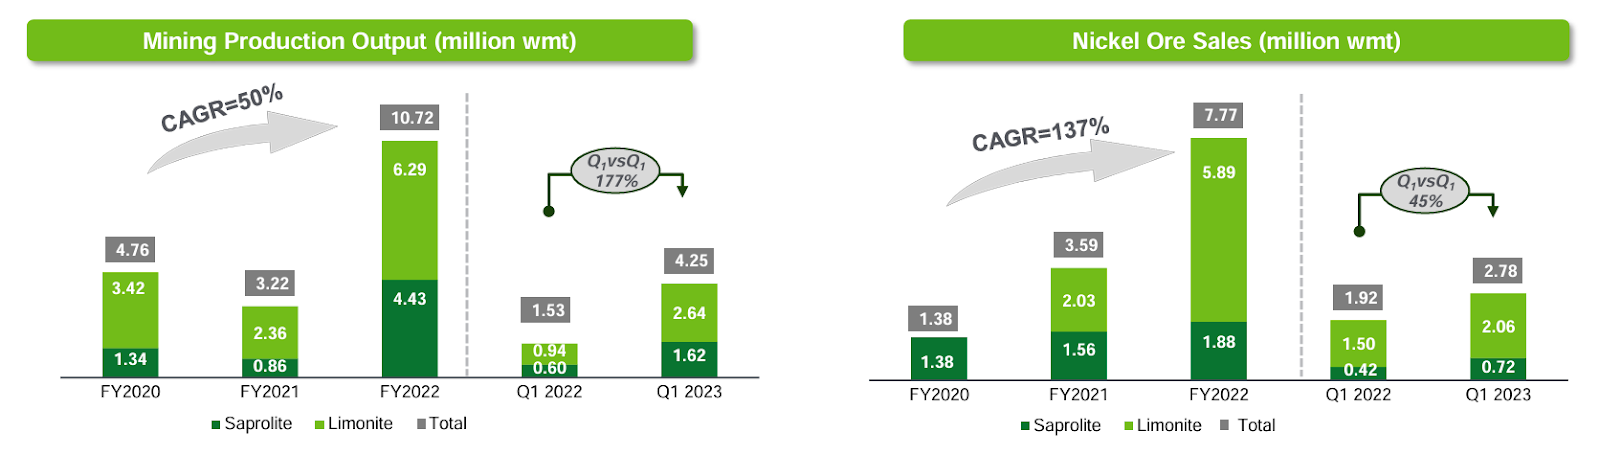
TBP's mining operation portfolio consists of 2 producing mines and 2 exploration-stage concessions on the Obi Island.
-
Moisture content is on average 30 - 35% for saprolite and 36 - 40% for limonite.
-
Nickel ore are sold to downstream operations at MSP and HJF and to our associate.
-
Strong growth in mining production and sales was due to the increase in nickel ore demand coming from the Group's processing businesses; RKEF smelter and HPAL refinery.
-
During FY2022 and Q1 2023, the increase comes from the 5 completed production lines' in RKEF nickel processing facility of PT HJF and commissioning of the 3ra line of HPAL in PT HPL.
-
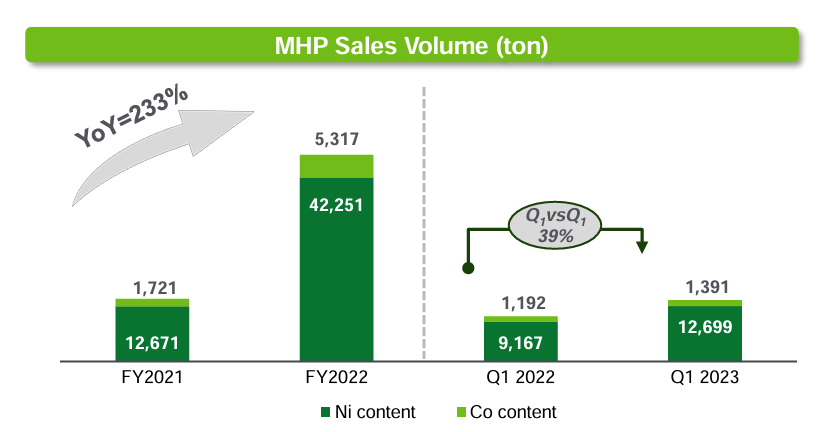
At the end of 2021, two MHP production lines of PT HPL have commenced its operation. First line ramped up to full capacity within 4 months and the second line ramped up only in 2 months.
-
The significant growth in FY 2022 was due to the improvement of the utilization.
-
The third line commissioned in January 2023 and ramped up to full capacity also in 2 months.
-
In Q1vsQ1, HPAL performances show a steady growth at around 36% for the production and 39% for the sales volume.
-
PT HPL started to produce Nickel Sulfate in April 2023, and expected to start producing Cobalt Sulfate in June 2023.