Investor/Analyst Briefing 1H25
1H25
Investor/Analyst Briefing Agustus 2025
-
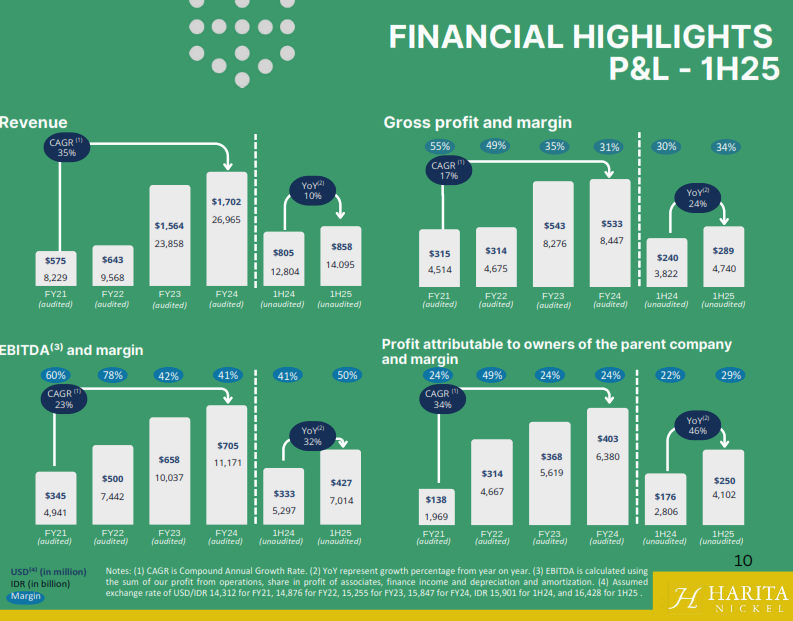
GPM is slightly higher, due to the company's operational efficiency improvements, then Gross Profit is up by 24%, EBITDA is up by 32%.
-
Profit Attributable to Owners of the Parent Company growth driven by higher volume in nickel processing (ONC and KPS) and the additional 10% stake in ONC, which applied using the equity method in 1H25.
-
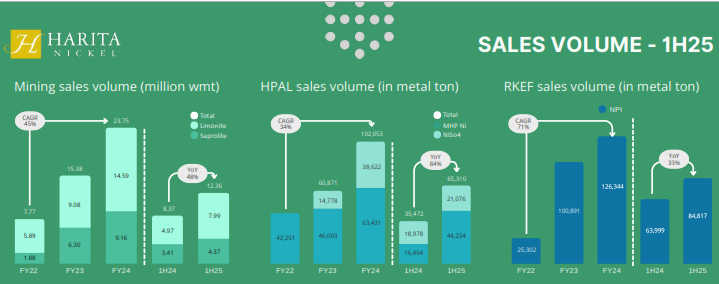
Higher sales volume mining business in 1H25 was due to capacity of ONC which commenced in April 2024. Additional to ONC, KPS (3rd RKEF smelter), commenced operation in January 2025.
-
In HPAL sales volume, ONC (full capacity in August 2024) is the driver of growth in MHP sales YoY. Both sales HPL & ONC in 1H25 reached 65,310 tons contained Ni, up 84% YoY. HPAL sales volumes in 1H25 are combination of MHP and NiSo4. Sales of HPL is 32,058 tons contained Ni and ONC is 33,252 tons contained Ni.
-
Significant growth of RKEF sales volume is due to KPS - phase 1 (which reach full capacity in March 2025). Sales volume of KPS - phase 1 in 1H25 reached 26,513 tons contained Ni of FeNi. Overall sales volume of FeNi up 33% YoY.